The question behind the question
Should you file a home insurance claim for water damage? In Moorpark, the answer rests on three numbers and one plan: the written repair estimate, your deductible, what the damage might still grow into, and whether you expect to sell soon. If the first number is plainly below the second, a claim may produce only a record in your file. If the damage is wet insulation, soaked subfloor or a ceiling that has begun to sag, the math changes quickly.
This is a decision aid, not advice about your specific policy. Your insurer and your agent can tell you how your policy treats notice, deductibles and claims history. Ask them before you decide, and ask whether a general question counts as a claim.
Four questions that sort most cases
Is the estimate near your deductible?
Get a written scope and price before you decide. If the repair is clearly smaller than the deductible, filing rarely pays and you carry the cost anyway.
Is the damage still being discovered?
Water wicks up drywall and travels under flooring. A small-looking loss can reveal a bigger one after moisture mapping, so a fast, honest inspection comes before the decision.
Will you sell or refinance soon?
Buyers and lenders ask about past water problems. Ask your agent and insurer how a claim and a repair record would each look to a buyer.
Is someone else responsible?
A failed fitting installed by a plumber, or a leak from a neighbor's unit in a condo, may involve another party's coverage. Document the source.
Decision table: file, pay yourself, or ask first
| Situation | Lean | Why |
|---|---|---|
| Small supply-line leak caught within hours and dried quickly | Often pay yourself if the estimate is under the deductible | A claim may produce nothing but a record, so compare the written estimate first |
| Water reached wall cavities, insulation or flooring across several rooms | Lean toward filing | Scope can grow after demolition and drying, and the deductible is a smaller share of the bill |
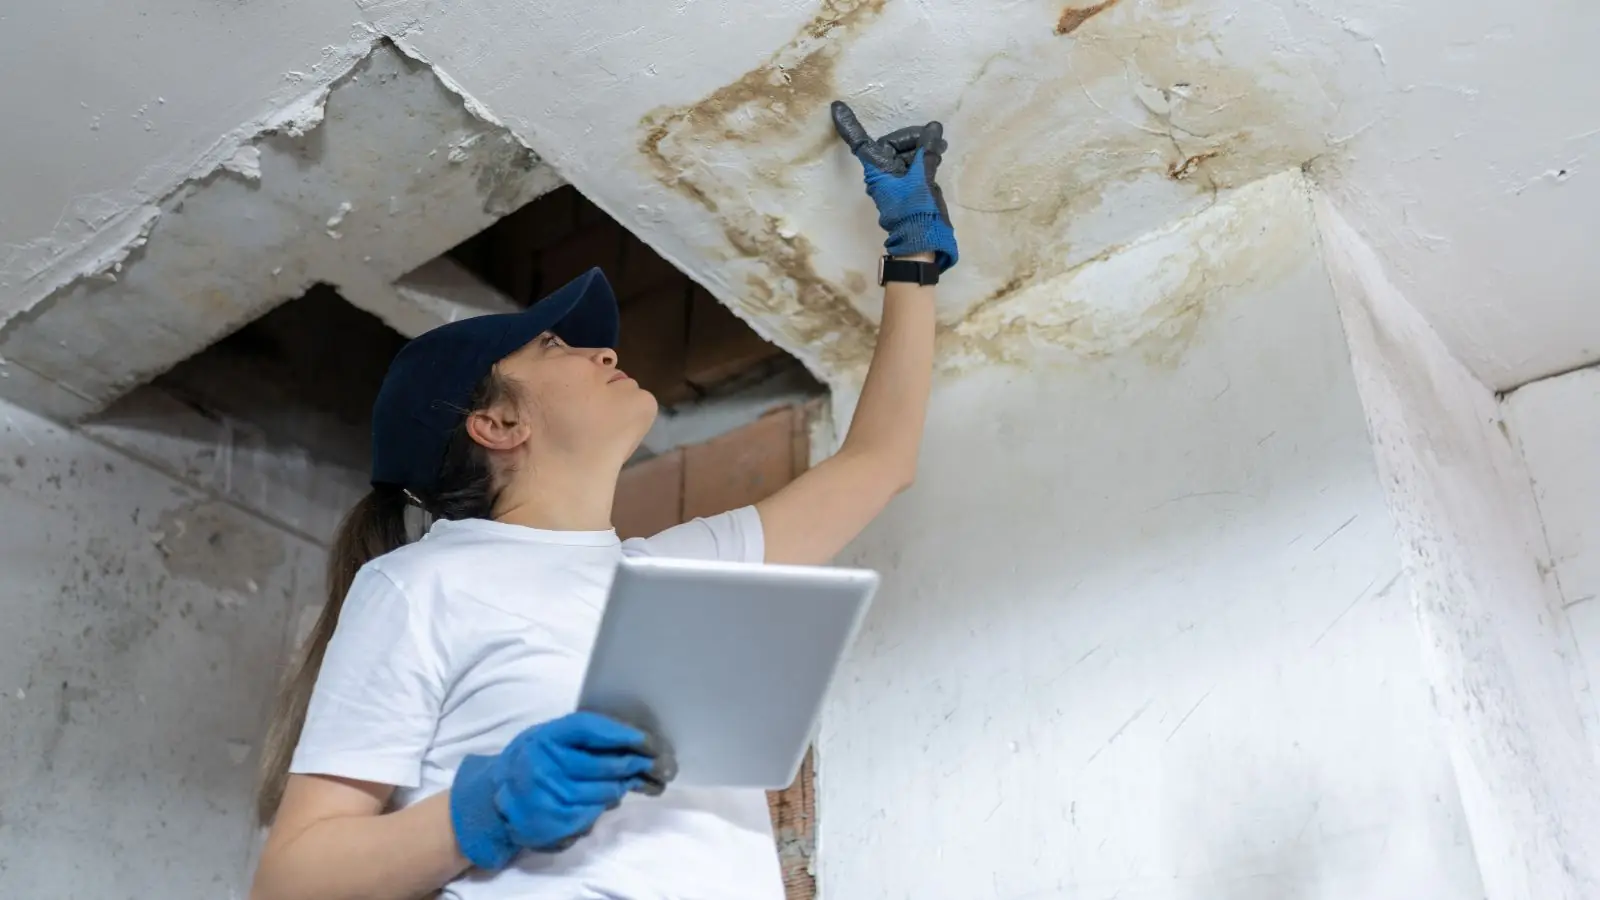
| Winter roof leak with a stained or sagging ceiling | Lean toward filing | Ceiling, insulation and attic work add up, and storm losses are what policies are written for |
| Sewage backup from a drain | Ask your insurer first | Backup coverage is often an endorsement, and Category 3 water raises the scope |
| Slow leak found late with softened wood | Ask your insurer first | Gradual loss is often excluded, so documentation and wording decide |
| Water from the street or a creek entering the house | Check flood coverage | Flood is generally not provided in a homeowners policy |
| Damage clearly under the deductible | Do not file, but keep records | Photos and invoices help if hidden damage appears later |
No row replaces a call to your insurer. The table is a way to arrive at that call knowing what you are asking.
Moorpark questions that change the filing decision
The City of Moorpark's flood map page says FEMA revised the city's flood maps for the Arroyo Simi and the Walnut Canyon Drain. According to the California Department of Insurance, flood losses are generally not provided in a homeowners policy. If water came from the ground or a street, a homeowners claim may be the wrong tool, so check the FEMA flood map for your address and ask your agent about flood coverage.
Winter is the usual season for roof and window leaks here. The city's normals list 3.21 inches of rain in an average January, 1.24 in April and 0.01 in July. A ceiling stain that appears after January rain and a stain found in July point to different sources, and an adjuster will ask which one you have.
For repair permits, ask your city building department. Moorpark City Hall is at 323 Science Drive. Knowing whether a rebuild needs permits before you compare bids keeps the estimate honest, and you can ask the same question of every contractor.
Want a scope before you decide?
Call 24/7. The the plan and price basis come before any work begins.
The deductible is only part of the arithmetic
A deductible is not the only price of a claim. Some insurers weigh claims history when they renew or quote, and the effect on premiums is something you can ask about in plain terms. Ask your agent whether a past claim could change your renewal, and whether an inquiry that never becomes a claim is recorded.
Delay is its own risk. Policies usually require prompt notice, so sitting on a loss while you think can complicate a later claim. A sensible path is to stop the water, get documentation and a scope, then decide within days rather than weeks.
Small losses can still be worth a call if they are not small underneath. Mapping moisture with meters and a thermal camera shows whether water reached the bottom plates of a wall or the insulation behind a cabinet. A crew doing water mitigation will tell you what is wet, what must come out and what can dry in place.
Selling a home after a water loss
Home sellers are generally expected to disclose known material problems, and past water damage is the kind of thing buyers ask about. The rules are specific, so ask your real estate agent and your insurer what applies to you. In general, a documented, professionally dried and properly repaired loss looks better to a buyer than an unrepaired stain.
That is a reason to keep the paperwork whether or not you file: the scope, the moisture readings, the invoices and photos. If mold appears after an old leak, mold remediation is a separate job that starts with fixing the water source. Buyers and lenders can ask for evidence that the problem was addressed, so keep records of both.
Homeowners in Simi Valley and Fillmore face the same sale-time questions, and the same advice applies: documentation beats memory.
Honest trade-offs
Filing gets you an adjuster, a scope and the possibility of payment. It can also bring a deductible, a claim record and a slower, more formal process. Paying yourself gives you control and speed but leaves you carrying the cost if the damage turns out bigger.
There is no universal answer, and anyone who gives you a dollar cutoff without seeing your policy is guessing. Collect the facts, then ask your insurer and your agent the specific questions in this post.
Questions readers ask
Past claims can appear in insurance records, and sellers are generally expected to disclose known material problems. Rules and practices vary, so ask your insurer and your real estate agent what applies to your situation. Keep the repair records either way.
Not one that fits every policy. Compare a written repair estimate with your own deductible, then ask your agent how a claim would affect your policy. Be wary of anyone who names a cutoff without reading your policy.
Waiting is risky. Most policies expect prompt notice, and wet materials degrade quickly. Stop the water, document the loss and decide within days.
You can ask. Coverage depends on whether the loss was sudden or gradual under your policy's wording, so keep photos of what was found and tell your insurer right away.